If your homeowners insurance company has asked for a roof inspection, it usually wants proof of two things: how old your roof is and what shape it’s in. Get the inspection done before your renewal date, fix anything small the inspector finds, and send your insurer the report and photos. Around Baton Rouge, Ryson Roofing does that free roof inspection for you.
Why your insurer wants a roof inspection
After several hard storm seasons, Louisiana insurers look closely at roofs before they renew a policy or write a new one. The roof is the part of the house that takes the most damage in a hurricane, so it carries a lot of weight in their decision.
The request usually shows up at one of these times:
- At renewal, especially when the roof is getting older
- When you switch to a new insurance company
- When you buy a home and set up a new policy
- After a claim or a big storm
Some insurers send their own inspector or look at aerial photos of your roof. Others ask you to send a report from a licensed roofer. Your letter or your agent will tell you which one they want and when it’s due.
Roof inspection or 4-point inspection?
A roof inspection looks only at the roof. A 4-point inspection covers four parts of the house: the roof, the electrical system, the plumbing, and the heating and air. Insurers often ask for a 4-point on older homes.
A roofer handles the roof part. The other three sections are done by a licensed home inspector. If your insurer sent a 4-point form, ask your agent who needs to sign each section before you book anyone.
What the inspector looks at
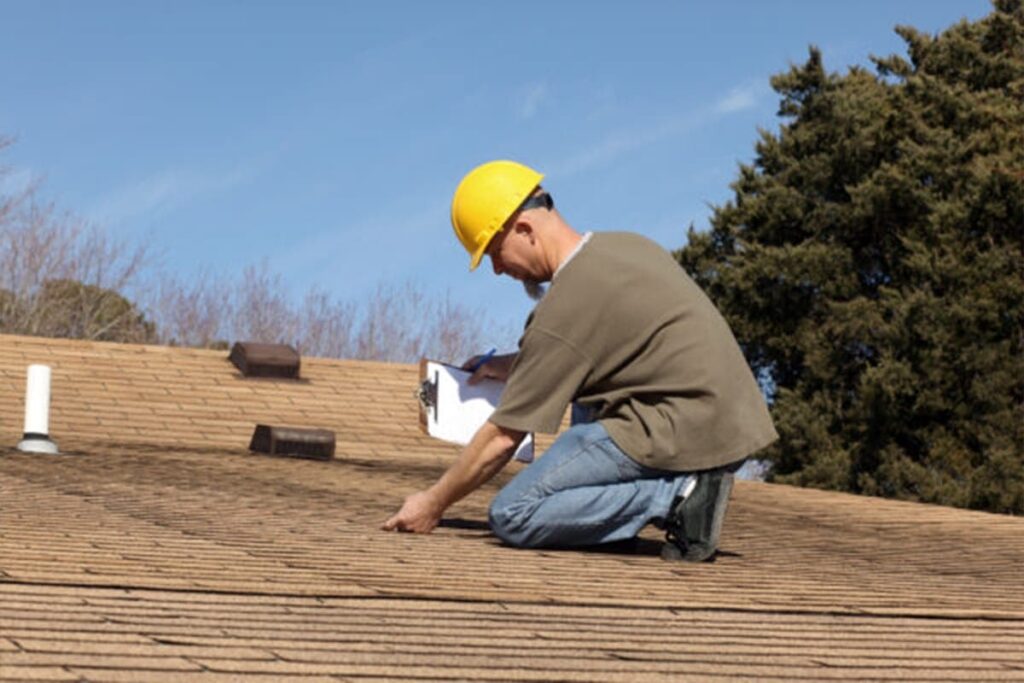
A roof inspection for insurance is mostly about documentation: dated photos and plain notes on what’s in good shape and what isn’t. On a Ryson inspection, the roofer checks:
- Shingles: granule loss, curling, cracks, and missing or loose shingles
- Flashing and seals: metal flashing at chimneys, vents and valleys, and old sealant
- Pipe boots and vents: small openings where water often gets in
- Gutters and drainage: clogs, sagging, and granules collecting in the gutters
- Attic: water stains, airflow, and daylight showing through the roof boards
- Roof deck: soft spots or sagging that point to hidden damage
Your insurer will also want the roof’s age. If you have the invoice or permit from the last replacement, keep it with the report.
How to get ready
- Read the letter closely. Note what the insurer is asking for, whether there’s a form, and the deadline.
- Find your paperwork. The year the roof went on, the invoice, the permit, and any warranty papers.
- Book early. Don’t wait for the week of the deadline, especially after a storm when roofers are busy.
- Ask for photos and a written report. A clear record is what your insurer can use.
- Fix the small things. A cracked pipe boot or a loose piece of flashing is often a quick repair. Keep the invoice.
- Send the report to your agent and keep a copy for yourself.
One of our customers summed it up in a Google review: their insurance company required a roof inspection at renewal, and Ryson was the only company that didn’t charge an up-front fee to look at the roof.
What if the roof gets flagged?
A flagged roof doesn’t always mean a new roof. Loose flashing, a few missing shingles or a worn pipe boot are usually a roof repair. Once it’s fixed, the invoice and new photos go back to your insurer.
If the roof is near the end of its life, the inspector will tell you plainly. Our guide to how long a roof lasts in South Louisiana shows what to expect by material. In that case a roof replacement may be the better path, because a new roof resets the age your insurer is looking at.
If the inspection turns up storm damage, that’s a different conversation. Our roof insurance claims page and the insurance claim process walk through what happens next, and our post on filing a wind damage roof claim in Louisiana covers the timelines.
If you replace, ask about FORTIFIED
A FORTIFIED roof is built to a standard from the Insurance Institute for Business & Home Safety, with a sealed roof deck and stronger nailing. Louisiana now ties it to your premium. The Louisiana Department of Insurance’s Regulation 136 requires insurers to give a discount on the hurricane part of the premium for homes with a FORTIFIED designation, no later than January 1, 2027. The size of the discount depends on where in the state you live.
A FORTIFIED Roof certificate is good for five years, and the state’s Louisiana Fortify Homes Program offers grants of up to $10,000 when a grant round is open. Our FORTIFIED roofing page explains how these roofs are built.
For your rights as a policyholder in general, the Louisiana Department of Insurance homeowners page is a good place to start.
Book your free roof inspection
Ryson Roofing is a family-owned roofer that has worked from 14858 South Harrells Ferry Road since 1999. We’re an Owens Corning Preferred Contractor and a CertainTeed ShingleMaster. A standard inspection is free, with no obligation, and you get photos you can send to your insurer. Not sure whether you need an inspection or an estimate? Here’s the difference between a roof inspection and a roof estimate.
Schedule your free roof inspection or call (225) 756-8603, any time, day or night.
Frequently asked questions
Is a roof inspection for insurance free?
A standard roof inspection from Ryson Roofing is free, with no obligation to book any work. You get photos and a written summary. If your insurer sent a specific form, mention it when you call so the inspector knows what to fill in.
What’s the difference between a roof inspection and a 4-point inspection?
A roof inspection covers only the roof. A 4-point inspection covers the roof, electrical, plumbing, and heating and air. A roofer handles the roof section, and a licensed home inspector handles the other three.
Can a roof inspection stop my insurer from dropping me?
It can’t change your roof’s age or force an insurer to renew. What it does is put real photos and facts in your file, and it catches small problems you can fix before the insurer flags them.
Does a FORTIFIED roof lower insurance in Louisiana?
Yes. Under Louisiana Department of Insurance Regulation 136, insurers must give a discount on the hurricane part of the premium for homes with a FORTIFIED designation, no later than January 1, 2027. The amount depends on your region of the state.
When should I schedule the inspection?
As soon as the request arrives, and ideally a few weeks before your renewal date. That leaves time to fix anything small and send the report before the deadline.